The following is an example of how to code in FACS an Eligible Individual with Ineligible Spouse for Household and Income Tabs.
Eligible individual with ineligible spouse. Ineligible spouse has earned income. Eligible QMBP.
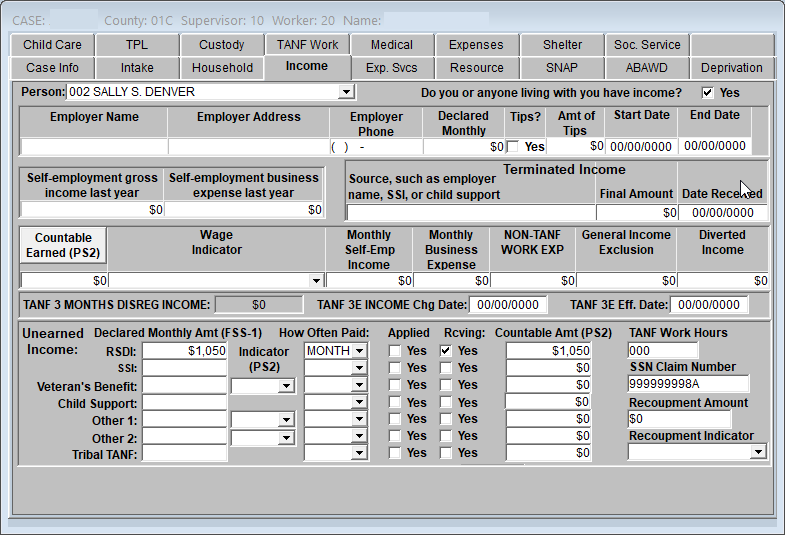
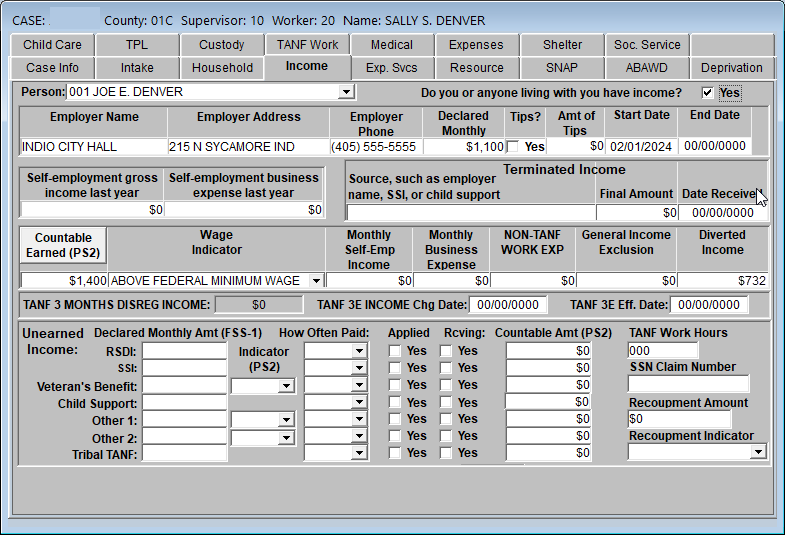
Sally is disabled and has $1050 in RSDI. She is also married to Joe Denver. Joe works and earns $1400 a month. Resources are verified as $1,600.
$1050 coded in RSDI tab.
Apply Earned Income Formula: (Gross Earned – $65)/2
Earned income deduction: ($1400 – $65)/2 = $667.50 ($668) countable earned income.
Diverted Income Calculation: $1400 – $668 = $732
Total Countable Income is $1050 + $668 = $1718
Because we have an eligible individual and an ineligible spouse, Sally must meet first as an individual and as a couple.
As an individual Sally’s income is $1050. She is eligible for QMBP.
As a couple the countable income is $1,718.50. She is eligible for QMBP.
Since Sally is eligible for QMBP, both as an individual and as a couple, we approve QMBP for Sally:
FACS coding for Income Tabs shown here:
Income Tab for Eligible Individual
Income Tab for Ineligible Spouse – earned income is entered in MICAL and diverted amount is coded.
Comments or Suggestions?
We want Quest to be your source for important information that you need to succeed at in your work but we need your help:
Was this article helpful? Was it missing something you needed to get the job done?
Tell us what you think, what you know about this article. What are we doing well, and what we could do better.
All fields are required.